An Unexpected $10,000 Says More About You Than Your Budget Ever Will
If you enjoy this article, please checkout The Financial Blueprint
Editor’s note: This week’s essay isn’t about investing, budgeting, or picking the right ETF. It’s about what your first instinct around money reveals before logic has a chance to intervene.
A few years ago, a friend of mine inherited some money from a relative she barely knew. Nothing dramatic. About ten thousand dollars. She mentioned it the way you’d mention the weather.
Then she mentioned what she’d done with it: nothing.
It had been sitting in her checking account for eight months. Not invested. Not spent. Not even moved into something that earned interest. Just sitting there, like she was afraid to look directly at it.
I asked why. She thought about it a second longer than the question should have taken.
“I don’t know,” she said. “It feels like if I touch it, it’ll disappear. Like it’s not really mine yet.”
She grew up in a house where money left fast, not recklessly, just constantly. Bills arrived before the paycheck did. She built an entire adult life around never feeling that again. Steady job. No debt. A rule she’d never said out loud but followed anyway: don’t trust money that shows up too easily.
She works in finance. She could have opened a brokerage account in four minutes. The ten thousand dollars wasn’t sitting there because she didn’t know what to do with it. It was sitting there because moving it felt, somewhere below the part of her she could explain, like proof it was never really hers.
That’s the part I keep thinking about: not what you’d do with an unexpected $10,000, but what you do with it in the four seconds before you’ve had time to rationalize anything. That reflex is the part that’s actually telling the truth. The decision you land on later is just what you talk yourself into.
Too small to hire an advisor for. Too large to lose track of. That’s the trap ten thousand dollars sets.
Nobody can spend it by accident, and no one steps in to decide it for you. It sits in a narrow gap with no script and nobody standing between you and the choice. Whatever you do with it didn’t come from a spreadsheet. It came from somewhere older than that.
Money doesn’t build who you are. People like to believe it would: that with more of it, they’d become generous, or calm, or finally disciplined. It doesn’t work that way.
What money does is take away the excuse. For years you’ve said you’d pay off the card once you had breathing room. Start the thing if you ever got a cushion. Give more, eventually, once there was actually more to give. Ten thousand dollars removes all of those excuses in the same instant.
What’s left standing there, with nowhere to hide, was already true before the money arrived. The windfall just turns the light on.
Ask seven different people what they’d do with it and you’ll hear seven answers, each delivered like it’s the obvious one.
A single parent sees it and thinks school fees, and feels, for once, the calculator in her head go quiet.
A founder thinks proof. Not permission. Proof, to herself, that the thing she’s been building quietly for two years isn’t a delusion.
Someone carrying $14,000 in credit card debt feels their shoulders drop half an inch before the math even starts.
Watching a parent count coins at the kitchen table leaves a rule behind: don’t touch it. The smart move has nothing to do with it. Touching it would mean finding out whether it was ever really theirs.
Three years of almost taking a trip, and it’s finally now. Not later, not when things calm down. Now, because the version of them that keeps waiting for a better time is exactly who they’re trying to stop being.
For someone else, barely a reaction. Indifference is a reaction too.
And someone whose mother raised four kids alone thinks of her before they think of themselves.
Behavioral economists have names for pieces of this: loss aversion, the house-money effect, scarcity’s habit of outliving the scarcity that caused it. The names are useful if you want the vocabulary. But you didn’t need any of them to recognize someone in that list. Some of them were probably you.
That’s the only honest data you’re going to get.
Most of us skip right past it, embarrassed by how unfiltered it is, hunting for the responsible-sounding answer instead.
Don’t.
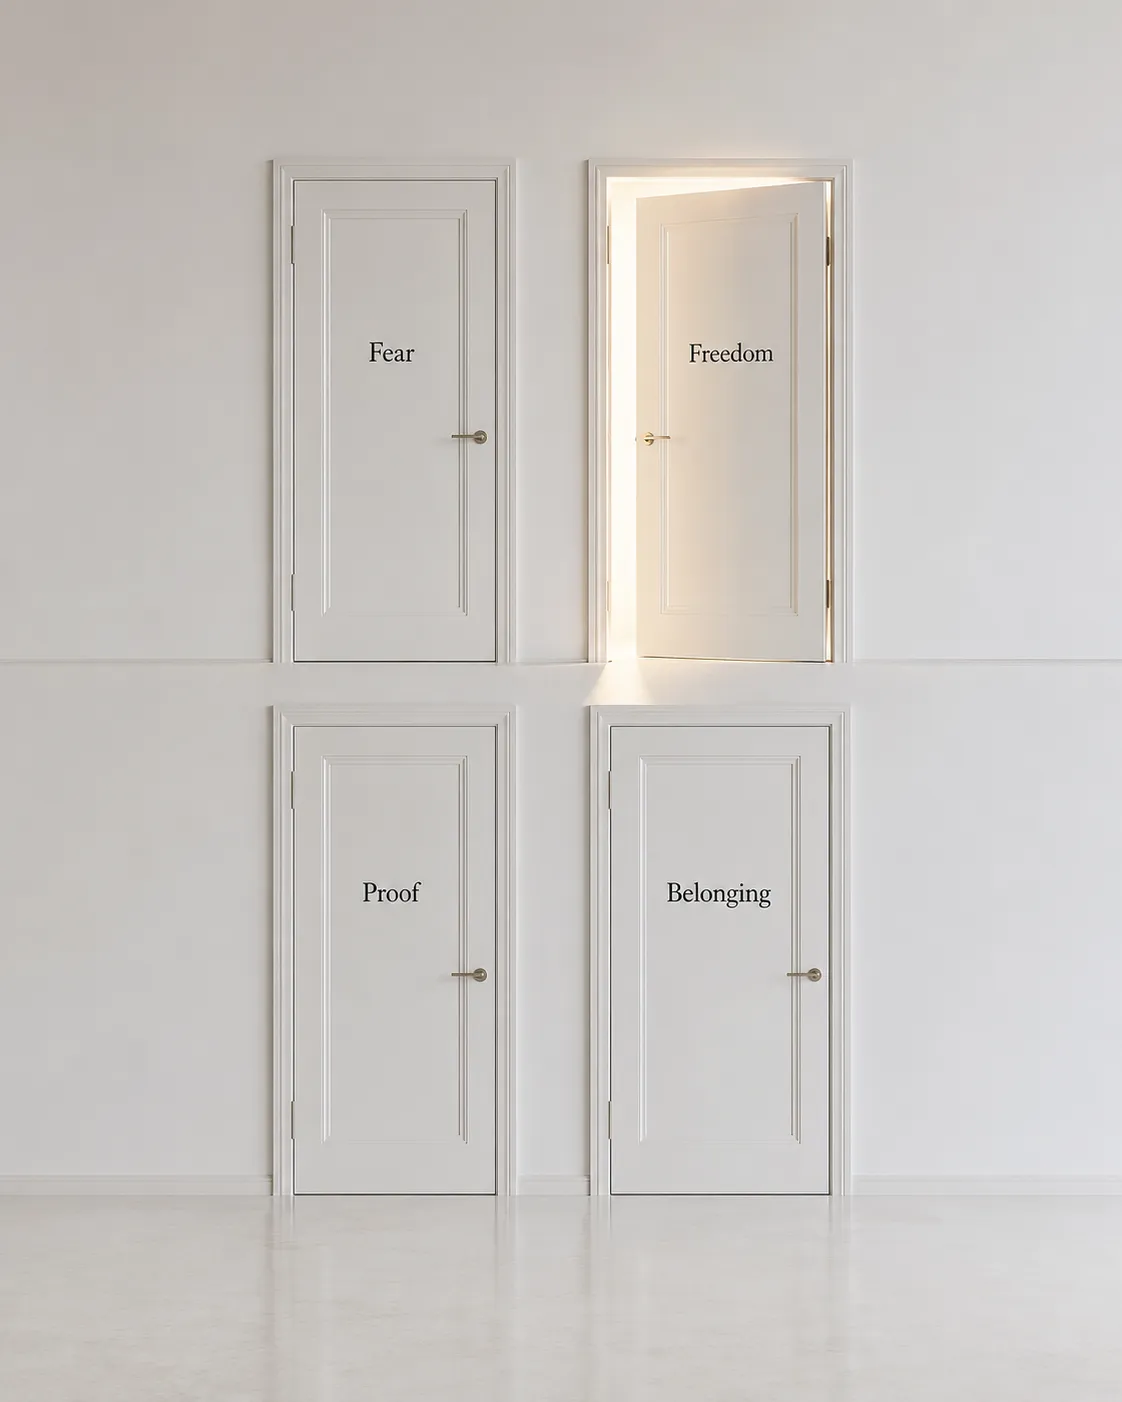
It’s almost always doing one of four things. Removing a fear: the debt, the instability, the thing that’s been quietly loud in the background. Reaching for freedom: room to breathe, room to choose. Chasing proof: evidence, to yourself more than anyone else, that you’re who you’ve believed you are. Or it’s about someone else entirely: a parent, a kid, a version of belonging that outranks the money itself.
Fear.
Freedom.
Proof.
Belonging.
Notice which one showed up in your four seconds, and you’ll know more about your actual financial life than a budget has ever told you. The reflex isn’t necessarily the right answer. It’s just the true one, and you can’t build a good decision on top of a dishonest one.
Here’s the part that’s easy to miss.
Your first instinct deserves your attention.
It doesn’t deserve complete control.
If your instinct was fear, don’t shame yourself for it. Ask what that fear is trying to protect. Then decide whether leaving the money untouched actually solves that problem or simply delays it.
If your instinct was freedom, make sure you’re buying options rather than escaping discomfort. There’s a difference between spending that creates flexibility and spending that creates another monthly payment.
If your instinct was proof, be careful. Windfalls have a way of tempting us to prove something, whether it’s to ourselves or to everyone else. The market doesn’t care whether you’re trying to validate your identity. Neither does your bank account.
If your instinct was belonging, generosity is one of the best uses of money. Just remember that helping others becomes much easier when your own financial foundation is strong.
The goal isn’t to eliminate emotion from financial decisions.
It’s to separate recognizing an emotion from obeying it.
That’s where good financial decisions begin.
I checked in with my friend recently. It’s been over a year. The ten thousand dollars is still sitting there, still untouched, still doing nothing.
She’s not confused about the math. She’s just not ready to find out what moving it would mean about her.
Which is the real answer, if I’m honest. Not what you’d do with an unexpected ten thousand dollars. What you’re already doing, right now, with the money you have. No windfall anywhere in sight. Because the money was never the decision. It was only ever the first thing honest enough to catch you making it.
Ten thousand dollars doesn’t build character. It just finally turns on a light in a room you’ve been furnishing your whole life.
If you enjoy this article, please checkout The Financial Blueprint