Is the Government fixing the wrong ISA problem?
Come 2027 the ISA may look slightly different. Here are the “Key Facts” presented by the government:
- Cash ISA limit (under 65): £12,000
- Overall ISA limit: £20,000
- No transfer from Non Cash ISA -> Cash ISA
- Start date: 6 April 2027
For those who don’t know, the main change here is that the cash ISA limit has been reduced from £20,000 a year to £12,000 if you are under 65.
Why are they doing this?
Brits bloody love their cash:
The UK currently has a chronic lack of people investing, especially when you compare to what the Americans do in their 401k’s. We are strangely obsessed with cash.
13.4 million Brits have a Cash ISA only
Despite there being so many more people with just a cash ISA, the value of what’s in the Stocks and Shares ISA is perhaps strangely much bigger as you will see in the graph below.
This is largely due to the low interest rate period of 2009-2022 where any cash savings were particularly unattractive.
And the better growth rate of stocks and shares will help keep the figures that way round, with the market value of Stocks & Shares ISA holdings up 18.7% in 2023/24 alone.
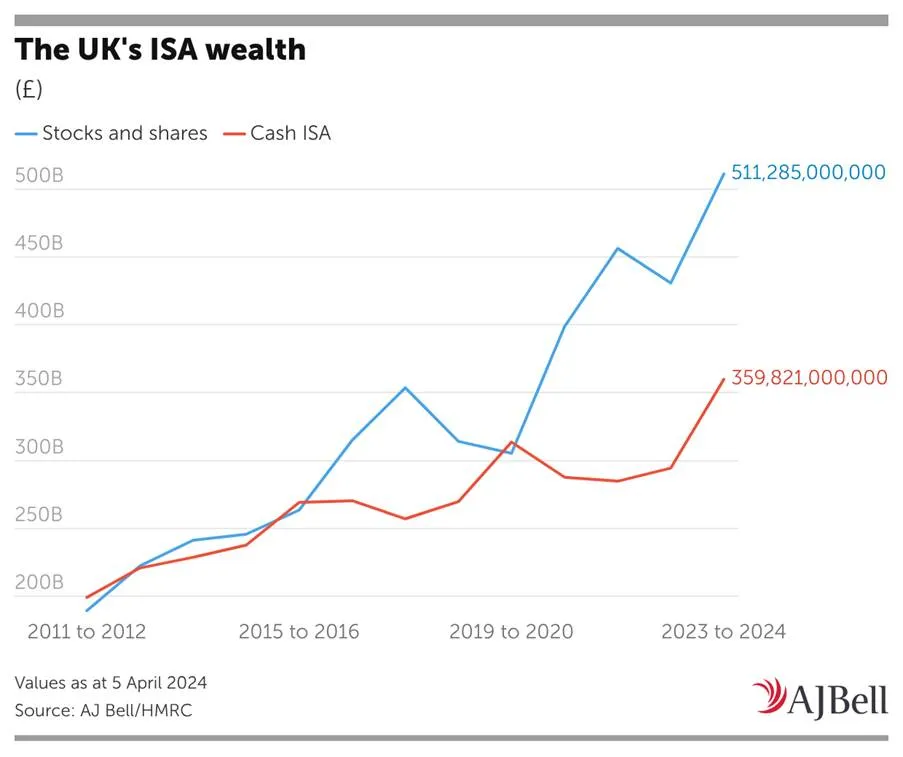
However, cash is making a comeback. Since 2022, rising interest rates have flipped the flow of new money. Cash ISA subscriptions rose 125% while Stocks & Shares ISA subscriptions fell 9% over the same two-year period.
As I said, Brits bloody love their cash.
Now I hear you cash lovers cunningly thinking “Well I’ll just put my cash in my stocks and shares ISA and use the full £20,000 allowance, it gets the same interest rate.”
Well the government are one step ahead of you here. You won’t be able to have cash or cash like instruments (think money market funds) in your stocks and shares ISA without being taxed 22% on the profits they generate.
However, this is where things get a bit murky. It isn’t completely clear if you will still be able to keep a bit of cash in your stocks and shares ISA, and the above tax only applies if everything in there is cash.
There is mention that a “well diversified portfolio” in a stocks and shares ISA will keep its tax wrapper.
Having cash is completely normal for investors who aren’t sure about a frothing market, or just don’t know what they want to do with it.
How will they decide what a “well diversified portfolio” is? By whose standard is this set? Benjamin Graham, or the new kid on the block who is YOLO’ing on chip maker stocks.
Are there going to be finfluencers and finance Substackers hired by the government to sit and go over everyone’s portfolios to decide if it’s diversified or not?
“A technical consultation with industry on the draft legislation will commence shortly”
So we will have to wait and see.
Is this the right plan?
I get why the government are doing this, we really need to get the cash that is stuck under people’s mattresses out and into long term investments.
As the triple lock pension becomes increasingly unaffordable, it’s becoming clear that millennials like myself are going to have to provide for a large part of their retirements.
This is why I can’t help but think that they should have just focused on incentivising people to invest in Stocks and Shares ISA’s rather than limiting Cash ISA’s.
The focus should be on the 60% of adults that don’t have an ISA at all, and to add to that the 31% have less than £1000 in emergency savings.
These rule changes seem like a hopeful fix in order to change a deeper underlying issue that could well backfire and lead to less money in cash ISAs, but nothing extra invested.
The UK desperately needs growth, that is why there was an idea floating around that people should be given an extra allowance for investing in UK stocks. Whilst there would certainly be some wrinkles to iron out in making this work, I’m thoroughly behind this idea.
The government could even match a certain amount you put in, similar to how they do with LISA’s. This would incentivise more companies to go public in the UK and existing ones to stay in the UK.
Only 20.5% of cash ISA holders used the full £20,000 allowance in 2022–23 – that’s around 3% of UK adults.
These products should be simplified, not complicated. If people already don’t want to put their money in Stocks and Shares ISA’s, adding more ways to get taxed through them isn’t going to help.
Adam’s advice to the UK government:
1 - Don’t add any tax complications to Stocks and Shares ISAs, people already think it’s too complicated.
2 - Offer an incentive for the cash hoarders to invest in British stocks.
3 - Focus on getting every adult an ISA, rather than limiting the minority who already do.
4 - Subscribe to this Newsletter (Come on John Healey, i know you want to).